
US Bank Earnings: What Would Justify Elevated Share Prices?
Intro
Can strong bank profits justify share prices that already reflect strong expectations? The supplied earnings preview puts JPMorgan Chase, Citigroup and Wells Fargo at the centre of that question, with reports scheduled for October 13. It also describes a market near historical highs, but provides no published quarterly results or verified valuation ratios. This is therefore a framework for assessing the reports, rather than a verdict on results already delivered. The key question is whether the banks can produce earnings that are repeatable without taking greater credit risk.
What the available prices actually tell us
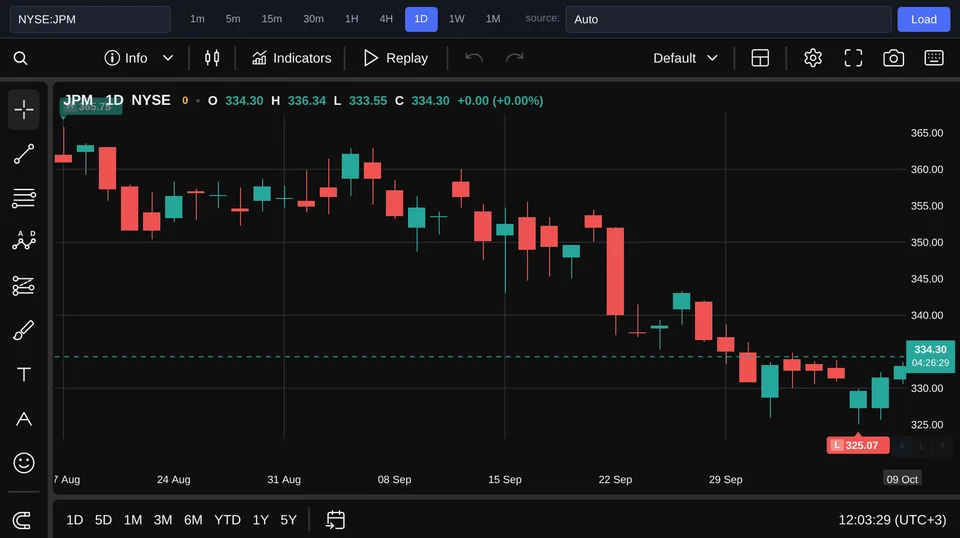
At the time of writing, the supplied market snapshot places JPMorgan Chase at 334.3 USD, up +0.39% for the day, and Wells Fargo at 83.32 USD, down -0.28%. Those are the concrete price observations available here; no corresponding Citigroup quote is supplied. The different directions show that these two shares were not moving together, but they do not establish why investors bought one and sold the other. A share price is an observation; an explanation for its movement is a hypothesis. These changes could reflect expectations about earnings, broader positioning or company-specific considerations, but the supplied information cannot distinguish among them. Nor does an absolute share price establish that a stock is expensive: that requires comparison with earnings, capital and a realistic view of future returns. The preview's references to record profits and stocks near historical highs describe the expectations being tested, rather than independently established financial findings. That distinction matters because a bank can report excellent profits and still disappoint investors who expected more. Markets occasionally arrive at dinner having already eaten the dessert; an impressive headline may have been priced in before it reaches the table. The useful test is whether the reports strengthen the case for future earnings. To answer it, investors need to separate recurring income, operating costs and credit losses from items that flatter a single quarter. The three banks should be assessed individually, because the same headline profit can emerge from different combinations of lending, fees and balance-sheet decisions.
Three explanations for confidence in bank shares
The first possible explanation is durable improvement in the underlying business. Net interest income, broadly the interest earned on assets less the interest paid on funding, can support profits when lending returns hold up and deposit costs remain manageable. Fee income can add another source of earnings, while disciplined expenses allow more revenue to reach the bottom line. This explanation is strongest when several recurring sources support profitability.
Why earnings quality is the stronger working hypothesis
The editorial working hypothesis is that sustainable income, controlled costs and manageable credit losses offer the strongest foundation for elevated valuations. This is an analytical judgement, not a finding that any of the three banks has already met those conditions. It is preferable to a simple record-profit test because it addresses the capacity to earn again after the quarter ends. A record result is persuasive when its main drivers can persist. Begin with net interest income and the accompanying outlook: does management describe a stable earnings base, or does the result rely on conditions it expects to weaken? Then examine fees and expenses together, because revenue growth can lose much of its value if delivering it requires disproportionately higher spending. Credit quality completes the picture. Provisions reflect expected credit losses, while charge-offs record losses recognised on loans; they answer related but different questions. A lower provision should therefore be read alongside delinquency trends, charge-offs and management's explanation of borrower conditions, rather than treated automatically as proof of healthier lending. The alternative explanations remain relevant, but need stronger supporting evidence. A temporary earnings boost can legitimately improve capital, and a credible efficiency programme can support future returns before its full benefit appears in profit. Neither establishes a durable earnings improvement on its own. The working hypothesis becomes more compelling when revenue, expenses, credit performance and guidance all point in a consistent direction.
The observations that would confirm or challenge the case
Confirmation would start with management maintaining or improving its outlook for core income and explaining the assumptions behind it. A stronger case would also show that profit growth survives the removal of exceptional gains and does not depend chiefly on reserve releases. Expense discipline would need to appear alongside those revenue trends, rather than remain a promise for later quarters. Stable credit performance is an essential confirmation condition. Investors should look for delinquency and charge-off trends consistent with management's assessment, and for provisions that acknowledge emerging risks. Stability does not require every credit measure to improve; it requires deterioration, where present, to remain contained and compatible with the bank's earnings outlook. The hypothesis would weaken if guidance falls, funding costs squeeze income or expenses rise faster than revenues without a convincing explanation. It would also weaken if worsening borrower performance forces higher credit costs, or if exceptional items account for much of an apparently strong result. Each of these observations would challenge the claim that today's profits provide a dependable base for tomorrow's returns. The share-price reaction is supporting evidence, not a final judgement on earnings quality. A decline after a solid report may mean expectations were even higher, while a rally after a mixed report may reflect relief that feared problems did not emerge. Comparing the financial details with subsequent guidance and later results is more informative than treating the first market move as a definitive assessment.
Conclusion
Strong profits can support elevated bank valuations, but a record headline alone cannot establish that they are justified. For JPMorgan Chase, Citigroup and Wells Fargo, the decisive evidence will be recurring income, expense control, credit performance and a credible outlook. With no published results supplied here, the answer remains conditional: confidence is best supported when earnings strength survives scrutiny of its sources and management gives sound reasons to expect it to continue.