
Market-Neutral Spot-Futures Arbitrage on Bybit: The Basics for Holders
Market-neutral spot-futures arbitrage is a strategy in which a trader simultaneously buys cryptocurrency on the spot market and opens a position in the opposite direction in a perpetual futures contract. In professional (specifically professional) jargon, this is called “opening both legs.”
“Legs” in arbitrage trading are the separate parts of a trade that are opened simultaneously in different markets or instruments (for example, buying on spot and shorting futures). Their balance is critically important: if the volumes of the legs diverge, a neutral strategy will turn into a directional position and introduce unintended risk.
The purpose of a structure in which one leg is a perpetual is to reduce the result’s dependence on fluctuations in the asset’s price and generate income from the funding rate. When the funding rate is positive, holders of long perpetual positions pay holders of short positions, making the futures leg a source of income.
It is important to understand that a “market-neutral” strategy still does not eliminate risks. The funding rate may change, while spot and futures prices may temporarily diverge. Fees, slippage, margin requirements, and the exchange’s technical risks can also materially affect the final result.
How Market-Neutral Spot-Futures Arbitrage Works
Let us imagine the following situation.
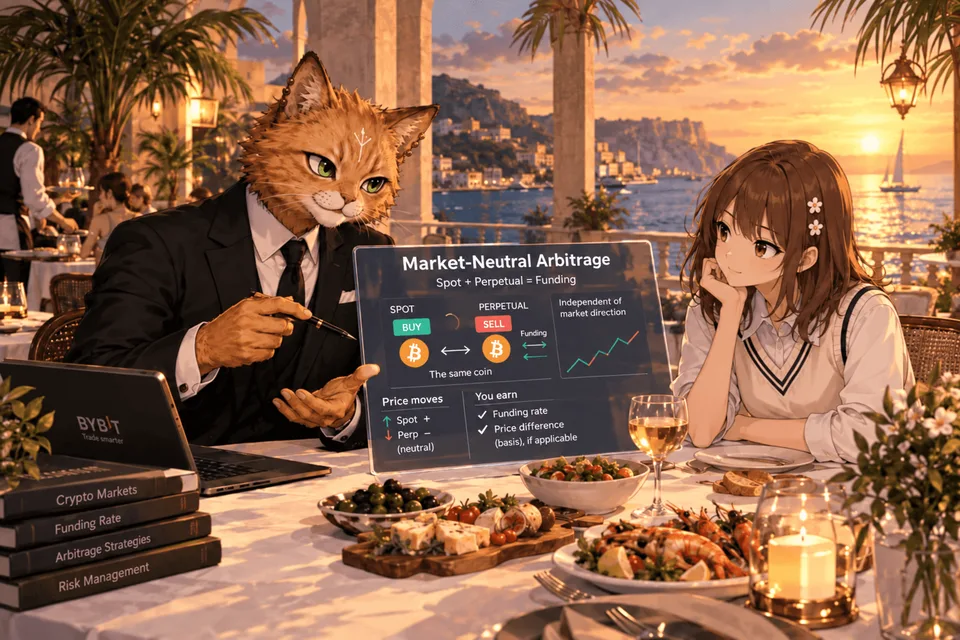
Suppose BTC is trading at $100K. A trader buys 1 BTC on the spot market for $100K and simultaneously sells 1 BTC through a BTCUSDT perpetual contract.
If the BTC price rises to $110K, the spot position will generate about $10K in profit, while the short futures position will incur roughly the same loss. If Bitcoin falls to $90K, the opposite will occur: the spot position will lose about $10K, while the short will earn approximately $10K.
With equal volumes in the two positions, directional price risk is largely offset. Formally, the structure can be represented as:
+1 BTC on spot − 1 BTC in a perpetual ≈ 0 delta
This is precisely why such a trade is called market-neutral.
Once again, we should note that near-zero delta does not mean zero risk: spot and futures prices do not have to move in perfect sync, and funding is not a fixed rate.
Where Does the Income Come From?
The main source of potential income in a market-neutral spot-futures arbitrage strategy is the funding rate.
A little theory.
A perpetual contract has no expiration date, so the exchange must keep its price close to the price of the underlying asset. A mechanism of periodic payments between participants is used for this purpose.
The rate is settled every 8 hours. With positive funding, longs pay shorts. With negative funding, the opposite occurs: shorts pay longs.
Thus, funding is a variable cash flow between traders’ open positions. The exchange does not collect funding, which is an important distinction from a trading fee.
The payment amount is determined by the position’s notional value:
Funding = position notional × funding rate
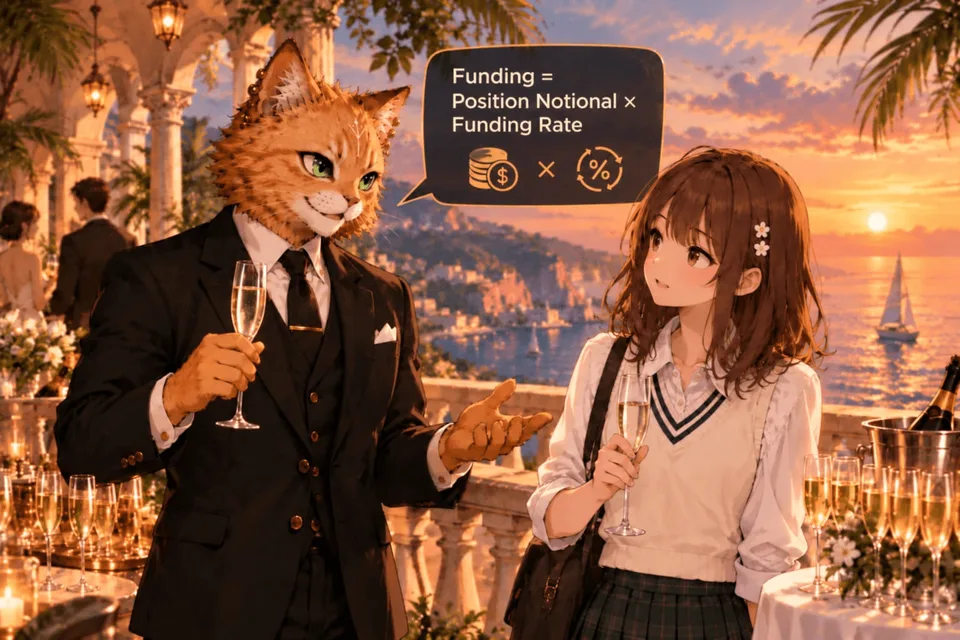
For example, with a $100K position and a rate of 0.01%, the payment will be $10 for one 8-hour period.
Funding cannot be regarded as a fixed return for several reasons, because the funding rate on perpetual futures is not constant. Bybit recalculates it every minute until the next settlement, so the value displayed on the screen is not guaranteed for the entire holding period.
This fundamentally changes the approach to the strategy.
A rate of 0.01% per eight hours is equivalent to approximately 0.03% per day when calculated simply. But this figure cannot be extrapolated over a month: after several settlements, funding may fall to zero or turn negative. Therefore, the history of rates actually charged over 7, 30, or more days is more important for evaluating a trade than the current rate.
How a Trade Is Structured on Bybit
The classic structure of a market-neutral trade is simple: a trader buys, for example, 1 ETH on Bybit’s spot market and simultaneously opens a 1 ETH short in ETHUSDT Perpetual. After that, the movement of the ETH price ceases to be the main factor in the result—the profit on one leg largely offsets the loss on the other.
Funding generates the main cash flow. At a positive rate, the short receives payments from the long; at a negative rate, the opposite occurs and the short pays. Hence the practical rule: if funding remains negative for a long time, the classic structure loses its main source of income and begins to work against the trader.
The Full Cost of the Trade
The complete formula for the costs of opening a trade is as follows:
trading fees + spread + slippage + funding + opportunity cost of capital + rebalancing costs.
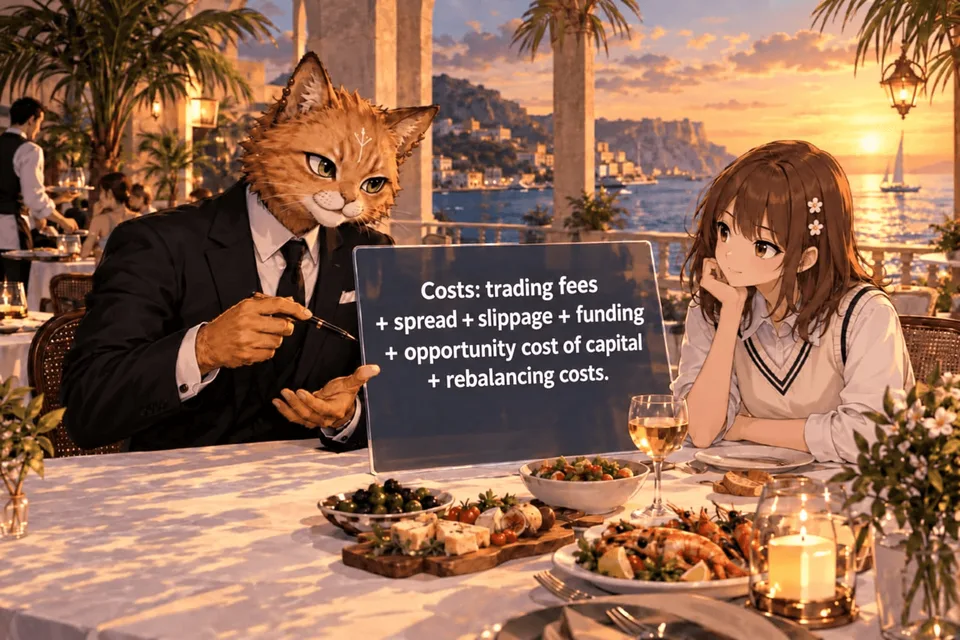
Bybit sets separate fees for spot and derivatives trading. At VIP 0, the base rate for crypto spot trading is 0.1% for makers and takers, while for perpetuals and futures it is 0.055% for takers and 0.02% for makers. Actual rates depend on the account’s region and VIP level—Bybit recommends checking the individual rate in the My Fee Rate section.
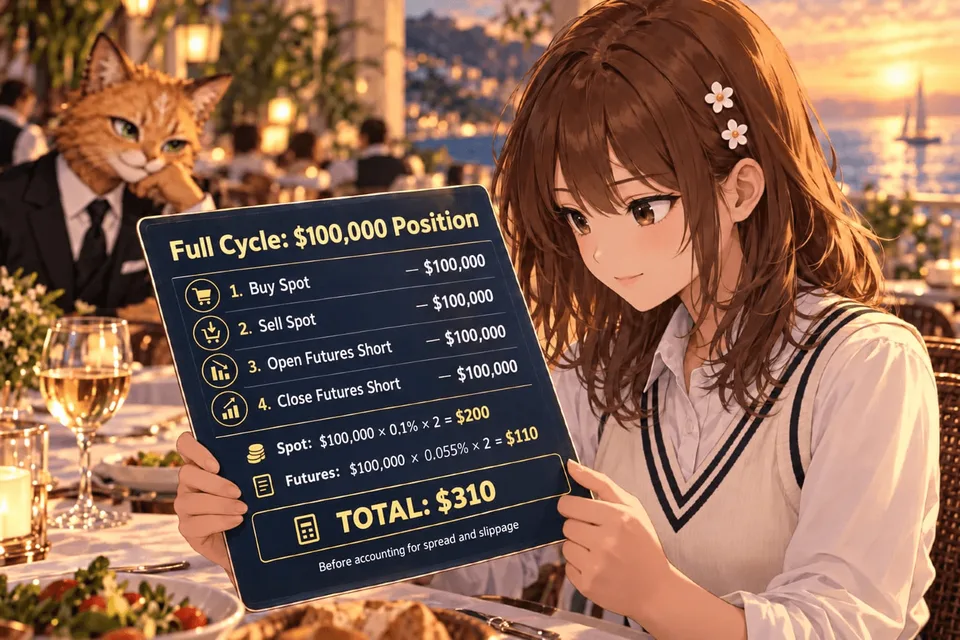
Consider a scenario involving market orders and the basic VIP 0 rates. With a $100K position, the full cycle consists of four trades:
buying the asset on the spot market—$100K;
selling the asset on the spot market when closing—$100K;
opening the futures short—$100K;
closing the futures short—$100K.
Cost of spot transactions: $100,000 × 0.1% × 2 = $200. Cost of futures transactions: $100,000 × 0.055% × 2 = $110. Total: $310 in fees for the full cycle—and that is before accounting for the spread and slippage.
Using maker orders reduces costs but introduces another uncertainty: an order may be filled only partially or may not be filled at the desired price at all. Choosing between maker and taker orders is a trade-off between cost and execution control.
How Much Funding Is Needed to Break Even
With $310 in fees on a $100K notional, the funding break-even point is: 310 / 100,000=0.31%.
Over 30 days, Bybit has 90 eight-hour settlements. To cover fees alone, the average funding per settlement must be: 0.31%/90≈0.0034%.
But this is only the fee threshold. The spread, slippage, and possible periods of negative funding must be covered on top of it. Therefore, a rate slightly above 0.0034% does not automatically make the position profitable—it merely breaks even on one cost item.
What to Consider Besides Funding
A positive funding rate is a necessary but insufficient condition for profitability. At least four factors stand between the expected-return calculation and the actual result, and each can partially or completely consume the funding gain.
Spread Between Spot and Futures
Even if the prices of the two instruments appear almost identical on the screen, entry will not necessarily occur at the same price. If spot is bought slightly above the expected price and the perpetual is sold slightly below it, part of the future funding is effectively spent as soon as the position is opened.
This is a hidden entry tax that is not visible in the funding rate but directly reduces the final result.
Slippage
A large market order is filled not at one price but across several levels of the order book, so the average trade price may differ noticeably from the quote on the screen. The larger the position volume relative to the depth of the order book, the greater the discrepancy.
On illiquid instruments, slippage can turn a theoretically profitable trade into a loss even before the first funding settlement.
Margin and Leverage
A futures position requires collateral. High leverage reduces the required margin but also decreases the safety buffer: free margin becomes small relative to the notional, and any temporary deterioration in conditions for the futures leg—a volatility spike or a change in the maintenance rate—increases the risk of liquidation.
For a market-neutral strategy, leverage is not an end in itself: it does not add returns but merely shifts risk from capital costs to risk management.
Rebalancing
Perfect neutrality assumes an equal amount of the asset on both legs. But if 1 BTC remains on spot while the futures short has fallen to 0.8 BTC because of a partial fill or manual adjustment, the trader has a net long position of 0.2 BTC—an unintended directional risk.
The volumes of the legs must therefore be monitored regularly: desynchronization is not always obvious and may accumulate unnoticed.
Opportunity Cost of Capital
Even if the exchange does not charge a separate fee for using the trader’s own funds, money has an opportunity cost: the $100K locked in the spot leg cannot simultaneously be allocated to another strategy.
When comparing arbitrage with alternative ways of deploying capital—deposits, staking, and other trading strategies—this implicit cost must be considered alongside fees and funding.
What Is Needed for Trading
For the first trade, it is more rational to choose one asset and one structure—for example, 1 BTC on Bybit spot and a 1 BTC short in BTCUSDT Perpetual.
Before opening the trade, four parameters must be checked: the current funding rate, the history of recent settlements, sufficient order-book liquidity, and the individual fee rate.
Then open both legs as synchronously as possible and make sure their notionals match.
After opening, attention shifts from the direction of the BTC price to four indicators:
the funding rate and its dynamics;
the ratio between the volumes of the two legs;
free margin;
the cumulative result after fees.
The BTC price remains important, but not as an object of prediction; rather, it is a factor affecting collateral and the size of the temporary divergence between positions.
When It Makes Sense to Close the Position
The holding period should not be tied to the calendar. A change in the economics of the trade is much more important.
A position that initially generated positive funding loses its purpose if the rate consistently approaches zero or turns negative. Another reason to reconsider the trade is a substantial widening of the spread between spot and futures or a reduction in available liquidity, making re-entry or rebalancing too expensive.
Thus, the lifespan of a position should be determined not by the number of days but by the relationship between expected funding and remaining costs. As long as the expected carry covers the costs, the position works. As soon as it stops doing so, it is time to close it, regardless of how much time has passed.
What Happened to Funding on Bybit in 2026
From April through September 2026, significant fluctuations could be observed in the amount of income generated by holding a position.
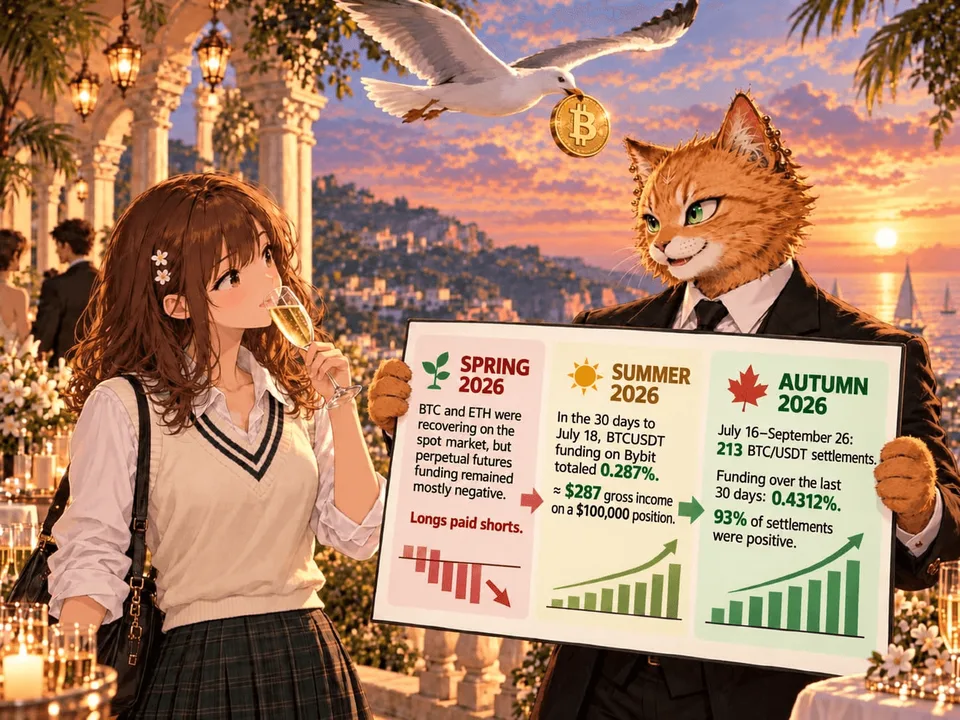
Spring 2026. According to Bybit, the recovery of BTC and ETH prices on the spot market proceeded without sustained support from perpetual futures: their funding remained negative most of the time. At that point, the classic “buy on spot and sell through a perpetual contract” strategy ceased to generate its usual funding income. Instead, the long position paid the short position.
Summer 2026. The regime changed. Over the 30-day period ending July 18, the funding actually charged for BTCUSDT on Bybit totaled 0.287%—about $287 in gross income on a $100K position for the month.
Autumn 2026. The positive regime for BTC persisted. In the PerpFinder database, 213 BTC/USDT settlements took place from July 16 to September 26, total posted funding for the last 30 days was 0.4312%, and 93% of the settlements were positive.
ETH showed similar dynamics.
Over the same 30 days through September 26, total funding for ETHUSDT was 0.3461%, with around 90% of settlements positive. However, negative charges also occurred within the period—even with a positive result for the month, the carry was not uniform.
SOL showed much sharper fluctuations.
At the end of July, funding for SOLUSDT was positive: on July 31, the rate was about 0.0065% per eight hours, while in individual settlements on July 29–30 it ranged from 0.0004% to 0.0064%.
In September, the picture changed: SOLUSDT history included both positive rates of +0.01% per eight hours and negative rates—−0.0106% on September 25 and −0.0091% on September 22. By the end of the month, positive values prevailed again: several consecutive settlements on September 27–29 remained around +0.01%.
Thus, over six months, three regimes successively replaced one another in the same market: first there was positive carry, then near-zero funding, and finally the short paid the long. This is why a market-neutral strategy depends critically not only on a single high rate but also on the stability of funding throughout the entire holding period. Individual rate values serve more as signals than forecasts.
Real-World Examples
BTC: Fees Consumed the Income
Take the 30-day period through July 18, 2026, when cumulative funding for BTCUSDT on Bybit was 0.287%. For a $100K position, that is: $100,000×0.287%=$287.
If the fees for four taker orders total $310, the result from these two items alone is: $287−$310= −$23.
Even positive funding for the month does not guarantee a positive result. This illustrates the strategy’s economics: a small decrease in funding or increase in execution costs is enough for fees to consume the income completely.
ETH: The Rate Is Too Low
According to Bybit, at the end of September 2026, cumulative 30-day funding for ETHUSDT was approximately 0.35%. With a $100K notional: $100,000×0.35%=$350.
With fees of $300+, about $40 remains—before deducting the spread, slippage, and other costs.
Even fairly stable positive funding for ETH does not provide a large margin if the trader enters and exits with market orders at VIP 0 rates. Reducing fees—by switching to maker execution or increasing the VIP level—changes the economics of the position more significantly than fluctuations in the funding rate itself.
SOL: Potentially Interesting, but Requires Monitoring
SOL presents a more complex picture. In September 2026, 30-day funding for SOLUSDT was significantly lower than the short-term peaks observed in individual settlements. At the same time, sharp shifts from negative rates to values around +0.01% per eight hours occurred within the month.
Suppose a trader saw a rate of +0.01% and decided to hold the position for a month. With a $100K notional, one settlement generates $10. A mechanical calculation of 90 such settlements yields $900. But this result is possible only if the rate remains unchanged throughout the period—and the actual history for September shows that this assumption is too optimistic: negative settlements occurred between positive ones.
For SOL, it is more reasonable to evaluate not the potential return from the current rate but the distribution of rates actually charged over the preceding weeks. A high rate at a given moment is not a forecast but one observation in a high-variance sequence.
Is It Interesting or Not?
Market-neutral spot-futures arbitrage is of interest to long-term holders of Bitcoin (BTC) or Ether (ETH), as the actual return on capital is low. In this case, it is essentially a relatively simple way to earn interest income on coins that are sitting idle and do not particularly need anything.
Speculative arbitrageurs should take a closer look at XRP, ZEC, SUI, LINK, HBAR, DOGE, NEAR, and HYPE. On the one hand, these instruments are sufficiently liquid; on the other, they have high funding. That is exactly what active arbitrage requires. But we will discuss that in another article.
Disclaimer
This material is for informational purposes and does not constitute investment advice.
Trading cryptocurrency derivatives involves the risk of losing capital, including the risk of forced liquidation.
Funding rates, fees, margin requirements, funding intervals, and other Bybit parameters may change. Before making a trade, you must check the current terms for the specific instrument and the account’s individual rate.