
July U.S. Inflation Test: PPI, CPI and the Window for a Fed Rate Cut
Introduction
The July block of U.S. inflation statistics became the market's main exam of the day: on the surface everything is calm, but under the hood traders are already recalculating probabilities, yields and risk appetite. Consensus expects PPI near 2.5% YoY and CPI near 2.4% YoY, which means there is room for a pleasant surprise, but it is narrow. The market now looks like a guest at the Fed's door: already holding his hat in his hand, but still not sure he is really being invited to the party of cheaper money.
Inflation: The Bar Has Already Been Set High
The main question of the day is not whether PPI near 2.5% YoY and CPI near 2.4% YoY will match forecasts literally to the tenth. Something else matters more: whether these figures will show soft enough dynamics for the Fed to move calmly toward a September rate cut without fearing a new round of price pressure. A soft inflation block will support the September rate-cut scenario, while hot data will quickly cool risk appetite. PPI is important as an early signal of pressure in the production chain, CPI as a check of whether that pressure reaches the consumer. If both releases come out in line with or softer than expectations, the market will get an argument in favor of easier policy; if at least one report proves noticeably stronger, rate expectations will have to be revised without needless lyricism.
Dollar: Cautious Weakness Before the Releases
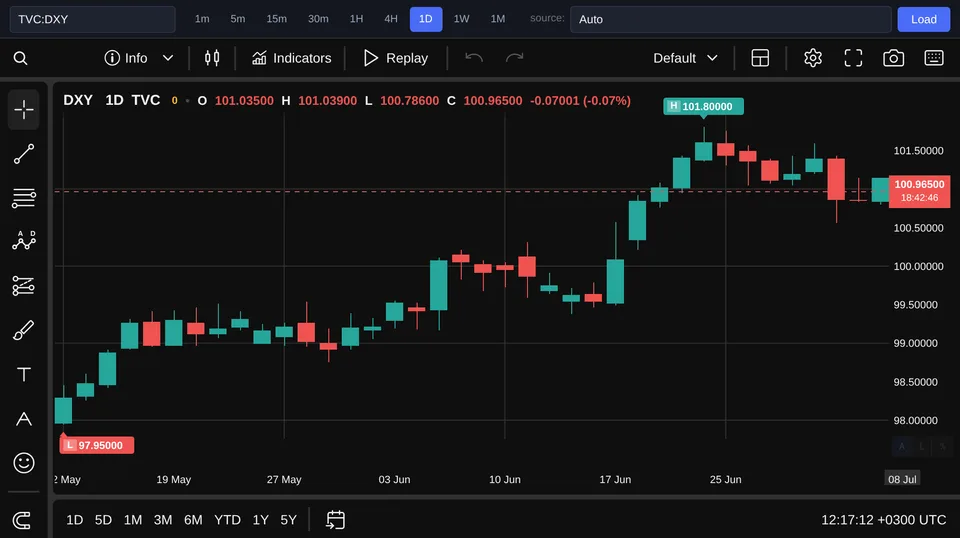
The DXY dollar index is holding near 101.0 USD and is down -0.08% on the day, which looks not like panic but like a careful reduction in demand for protection before the statistics. Traders are not yet rushing to buy the dollar aggressively because the scenario of September Fed easing remains alive. The current weakness in DXY shows that the market still allows room for a rate cut. But this signal is fragile: if CPI or PPI come in above expectations, the dollar may quickly recover together with yields, because the idea of “higher rates for longer” will again become a convenient support for the U.S. currency.
S&P 500: Locking In Optimism, Not a Reversal
The S&P 500 is at 7 483 USD and is losing -0.28% on the day, meaning stocks are pulling back slightly before important data but are not showing signs of a full-fledged flight from risk. This looks more like disciplined profit-taking than a rejection of the positive scenario. For stocks, the best option is inflation soft enough for the Fed, but not so weak that it scares investors with slowing demand. Investors need lower future rates because they support company valuations, but they do not need a macroeconomic cold shower. If the data come out moderate, the broad market may keep support; if inflation surprises to the upside, rate-sensitive segments will be the first to come under pressure, and then the whole index will be tested.
Fed: September Remains the Main Question
The Fed is not obliged to react to one perfect report; it needs a sequence of data confirming inflation's movement toward the target. That is why the market sees July PPI and CPI as a stress test for the autumn scenario, not as ordinary macro statistics from the calendar. The September rate-cut scenario will be best preserved if both reports confirm a slowdown in price pressure. At the same time, positioning is already fairly optimistic, so even data “in line with forecasts” may trigger an uneven reaction if the market has priced in too much good news in advance. It is worth watching not only the headline percentages, but also the synchronized reaction of rates, the dollar and stocks after publication.
Conclusion
The bottom line of the day is simple: the market is not waiting for a pretty number for the sake of the number itself, but for permission to keep believing in a softer Fed by September. DXY at 101.0 USD with a move of -0.08% shows cautious dollar weakness, while the S&P 500 at 7 483 USD with a change of -0.28% reflects moderate risk-taking before the releases. If PPI near 2.5% YoY and CPI near 2.4% YoY are confirmed or come in softer, the rate-cut scenario will receive support. If the data come out hotter, the market will quickly return to a tougher repricing of rates, the dollar and stocks. Practical takeaway for a Forex trader: the rule should be tested on a demo account, written into the trading plan and applied consistently before every trade. Practical takeaway for a Forex trader: the rule should be tested on a demo account, written into the trading plan and applied consistently before every trade. Practical takeaway for a Forex trader: the rule should be tested on a demo account, written into the trading plan and applied consistently before every trade. Practical takeaway for a Forex trader: the rule should be tested on a demo account, written into the trading plan and applied consistently before every trade. Practical takeaway for a Forex trader: the rule should be tested on a demo account, written into the trading plan and applied consistently before every trade. Practical takeaway for a Forex trader: the rule should be tested on a demo account, written into the trading plan and applied consistently before every trade.